

Current - Mobile Banking
4.5

I judge a money app less by the first few minutes than by whether it still earns a place on my phone once the novelty wears off. Current - Mobile Banking makes a strong first impression with an approachable layout and a focus on everyday money tasks. Its appeal is practical: checking spending, setting aside savings and receiving pay are all reasons to open it again, not just features to admire once. The important question is whether those routines match the way you already manage your finances.
Who is likely to get lasting value
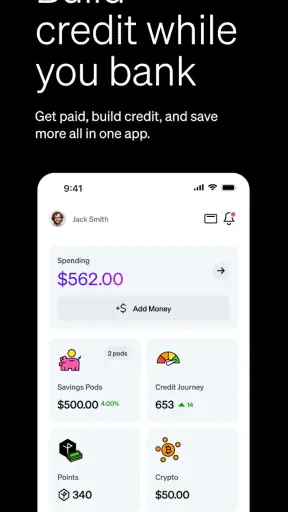
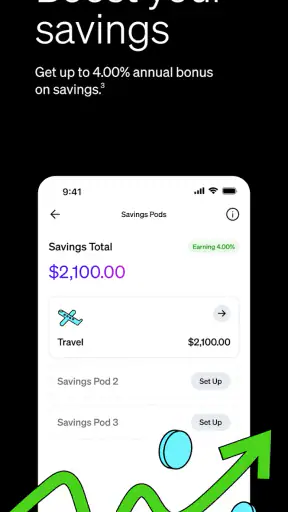
I can see this working well for someone who wants a phone-first way to keep an eye on day-to-day money, especially if spending alerts help them notice purchases while they are still fresh. Savings pods also suit people who find it easier to save toward a named goal than to leave spare money in a general balance. That small change in framing can make a planned expense feel more manageable: instead of mentally mixing travel money with grocery money, you can give the goal its own place.
It is less compelling if you mainly want a place to compare complex financial products, manage investments, or build a detailed household budget across several accounts. Current is a finance app, but that does not automatically make it a complete replacement for every financial tool. If your existing bank already gives you the account structure and budgeting detail you rely on, switching just for a cleaner interface may not justify the effort. I would first identify the specific habit you want to improve, then see whether the app supports that habit.
A useful routine, not just a quick setup
A realistic use case is a weekday lunch break: I check a recent notification, notice that a small purchase has nudged my spending higher than expected, and move a planned amount toward a savings pod before the rest of the day gets busy. The value is not that the app makes a decision for me; it gives me a timely prompt and a place to act. For this to remain useful, I would treat alerts as reminders to review, not as a substitute for checking whether upcoming bills and plans are covered.
One practical way to make savings pods work harder is to name each one for a real purpose and decide in advance what counts as a contribution. A vague “savings” goal is easy to ignore; a pod for a known trip or replacement purchase gives each transfer a reason. I would still leave a sensible cushion for ordinary expenses rather than moving every spare dollar into a goal. The trade-off is that goals can make saving feel clearer, but they do not remove the need to plan around irregular costs.
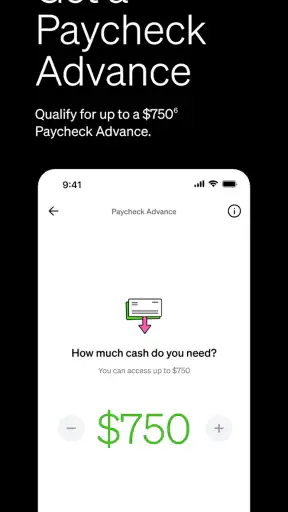
The early-pay option is most relevant to people who receive wages by direct deposit and care about the timing of money arriving. It may help smooth a tight stretch between paydays, but I would avoid building a budget that depends on pay arriving early every time. A safer routine is to plan around the normal pay schedule and treat earlier access as flexibility when it happens. That keeps a convenient feature from becoming a financial assumption.
How it fits beside familiar banking options
Compared with a traditional bank app, the appeal here is a more focused mobile experience: spending notifications and goal-oriented savings are prominent reasons to use it. A conventional bank may suit someone better if they prefer handling most financial tasks through an established branch relationship or want a broader set of services in one place. Neither style is automatically better. I would compare the daily tasks I actually perform—checking a balance, tracking purchases, moving money and paying bills—rather than choosing based on the word “modern.”
It can also sit alongside tools people already use rather than replacing them immediately. If you have direct deposits, recurring bills or savings habits tied to another account, changing everything at once adds avoidable friction. I would start by deciding which role Current should play, then give that role a consistent routine. For example, it might be the place I check spending while another account remains the home for a separate financial need. Keeping the roles clear makes it easier to spot whether the app is genuinely helping or simply adding another screen to check.
Some common questions are worth answering through that lens. Is it useful without direct deposit? The spending and savings tools may still be relevant, while the early-pay benefit depends on setting up direct deposit. Does a savings pod make money inaccessible or automatically protected from overspending? I would treat it as an organizing aid, not a substitute for understanding account terms or maintaining a separate cash buffer. Is it right for someone who rarely checks a phone? Probably not as a primary money tool: its strengths are most apparent when you use notifications and mobile access as part of a routine.
First Impressions: Setup and Interface
Jumping into the Current - Mobile Banking app was a breeze. The setup process is straightforward. You just download the app, sign up, and boom—you’re in. No complicated steps or unnecessary hoops to jump through. Right off the bat, I was impressed with how intuitive the interface is. It’s clean and modern, with everything laid out in a way that just makes sense. If you’re someone who appreciates a clutter-free experience, you’ll dig this.
Features That Stand Out
Now, let’s talk about what makes this app tick. Current offers a variety of standout features that make managing your money not only easy but kind of fun. You get real-time spending notifications, which is perfect if you want to keep tabs on your budget. There’s also a feature that lets you set up savings pods, so you can stash away cash for that vacation or new gadget you’ve been eyeing.
Another neat feature is the ability to get paid up to two days early if you set up direct deposit. Let’s be real, who doesn’t want their paycheck early? Plus, there are no hidden fees, which is a huge relief. I’ve lost count of how many times I’ve been hit with unexpected fees from traditional banks, so this was a welcome change.
User Experience: The Nitty-Gritty
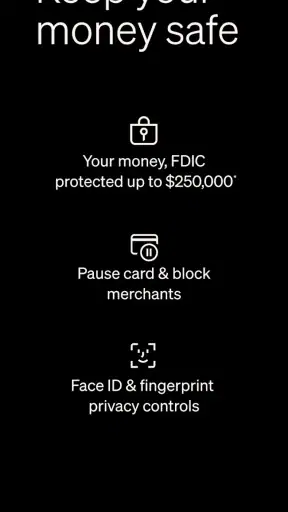
When it comes to user experience, Current really shines. Navigating the app is seamless. Whether you’re checking your balance, transferring funds, or paying bills, everything is just a tap away. The app’s speed is impressive, with no lagging or crashing in sight. I also appreciate the biometric login feature—adds an extra layer of security without being a hassle.
Support is another area where the app excels. If you ever run into issues, there’s a handy chat feature to get in touch with customer service. From my experience, responses are quick and helpful, which is always a plus.
Security: Peace of Mind
In today’s digital world, security is a big deal, and Current - Mobile Banking doesn’t skimp here. The app employs cutting-edge security measures to protect your data. End-to-end encryption, two-factor authentication, and instant card locking features ensure that your money is safe and sound. It’s comforting to know that they take your security seriously.
Plus, if you ever lose your card, the app has your back. You can lock your card with a simple tap until you find it or get a replacement. This kind of proactive approach to security is something every banking app should offer.
When everyday convenience starts to wear thin
Any app that depends on frequent check-ins can become another source of noise. Spending alerts are helpful when they catch a purchase I might otherwise overlook, but a steady stream of notifications can train me to dismiss them. I would keep the alerts that prompt a useful action and avoid treating every ping as urgent. The point is to make money easier to notice, not to make the phone feel like a running commentary on every transaction.
There is also a maintenance cost to using a second financial app: I need to remember which account holds which money, where recurring payments come from, and whether a transfer is still pending before I count on it. That is not a flaw unique to Current, but it matters when deciding whether another app improves the system or complicates it. A simple written note of each account’s role, reviewed when bills or income arrangements change, can prevent the convenience of a tidy interface from turning into confusion.
For anyone thinking about moving their main banking routine, I would make the transition deliberately. Start by checking which payments, deposits and savings goals would need attention, then change one part at a time rather than closing an old setup immediately. This is especially sensible if rent, utilities or other essential payments rely on an established account. A smooth-looking app does not remove the practical work of changing where money arrives and leaves.
The month-to-month test
Current’s long-term value depends less on how polished the first session feels and more on whether its tools solve a recurring problem. If notifications help me catch spending early and pods keep a goal visible, I have a reason to keep opening it. If I stop using those tools after the first few weeks, the app may become just another place to check a balance. I would give it a fair trial tied to a specific routine—such as reviewing spending after payday—rather than expecting the interface alone to change my habits.
Current is developed by Current, and it is free to install. It has a 4.5 average from around 176,000 ratings, with more than five million installs and about 47,000 written reviews. The app is rated for Everyone, and version 8.3.2 requires Android 8.0 or later. Those figures suggest it has reached a sizeable audience, but they cannot tell me whether its particular workflow suits my needs; that still comes down to trying the routine I intend to use.
Final Thoughts
Wrapping it up, Current - Mobile Banking is a solid choice for anyone looking to manage their finances with ease and efficiency. It’s packed with features that cater to modern banking needs while maintaining a user-friendly interface. Whether you’re tech-savvy or someone who’s not super into gadgets, this app is designed to be accessible to everyone.
If you’re tired of dealing with traditional banks and their endless fees, or just want a more streamlined way to handle your money, give Current a try. With its robust features and emphasis on security, it might just become your go-to banking solution. So, go ahead and download it; your future self may thank you!
My long-term verdict
I would keep Current if it makes one repeatable part of managing money noticeably easier: catching spending promptly, setting aside cash for a defined goal, or making mobile access feel less cumbersome. I would not keep it merely because the first setup felt effortless. A finance app earns lasting space when it supports a habit without demanding constant attention, and that is the standard I would use here.
For someone who wants a clear, phone-centered way to handle routine money tasks, it is worth considering. Someone who needs a different set of services, prefers in-person banking, or already has a dependable system may be better served by staying with that arrangement. My recommendation is to choose a concrete job for the app, use it consistently, and judge it by whether that job remains easier after the initial appeal has faded.
4.5
46.90K Reviews
Pros
- User-friendly interface for easy navigation.
- Instant notifications for transactions.
- Secure login with biometric options.
- Wide range of financial management tools.
- Seamless integration with other financial apps.
Cons
- Limited customer support availability.
- Occasional app freezes and crashes.
- Some features require in-app purchases.
- Not all banks supported for linking.
- Initial setup can be time-consuming.


